Cameron tracked every loan in a beautiful spreadsheet: color-coded, with formulas for balances and a tab per person. Then Reese, who owed $1,800, said they’d already paid $600 that wasn’t in it. Cameron’s spreadsheet was perfectly accurate about what Cameron believed, and it couldn’t settle anything. That’s the heart of the IOU app vs spreadsheet question: not which tool is smarter, but whose agreement each one records. Here’s an honest comparison of notes, chats, spreadsheets and a signed record in IOUEZ.
Key takeaways
- Notes and spreadsheets are one-sided. They record what you think. Nobody else agreed to them.
- Chats are two-sided but scattered. The agreement is in there somewhere, mixed with memes and dinner plans.
- A signed record is shared and fixed. Both people agreed, both see the same numbers, and the core terms can’t drift.
- Spreadsheets still win at analysis. Use one for budgets and totals; just don’t let it be the only record of a loan.
Four ways people record a loan
Most people already use one of these. None of them is wrong; they just do different jobs.
A notes app (“Reese $1,800, Aug”). Fast, private, always on your phone. A chat thread (“ok so 300 a month starting sept?” “yes!! thank you”). The real conversation, with both voices in it. A spreadsheet, with dates, payments and running balances. Flexible and free. A signed record in an app like IOUEZ: an agreement both people sign, with payments both can see.
| Notes app | Chat thread | Spreadsheet | Signed record in IOUEZ | |
|---|---|---|---|---|
| Who agreed to it | Only you | Both, informally | Only you | Both, with signatures |
| Can terms change quietly? | Yes | No, but they get buried | Yes, any cell | No, core terms lock once both sign |
| Both see payments | No | Only if mentioned | Only if shared | Yes, live on both accounts |
| Reminders | No | You send them | No | Day before, on the day, and if overdue |
| Totals and analysis | Weak | None | Excellent | Per-currency balances, filters |
| Cost | Free | Free | Free | Free account; paid plans add more |
| Easy to find in 3 years | Maybe | Hard | Yes | Yes, plus PDF and CSV copies |
We marked the signed record column, but look at the spreadsheet’s analysis row honestly. For totals, budgets and “what if” math, nothing beats a spreadsheet. The trouble is only when it’s asked to be proof.
The IOU app vs spreadsheet question, side by side
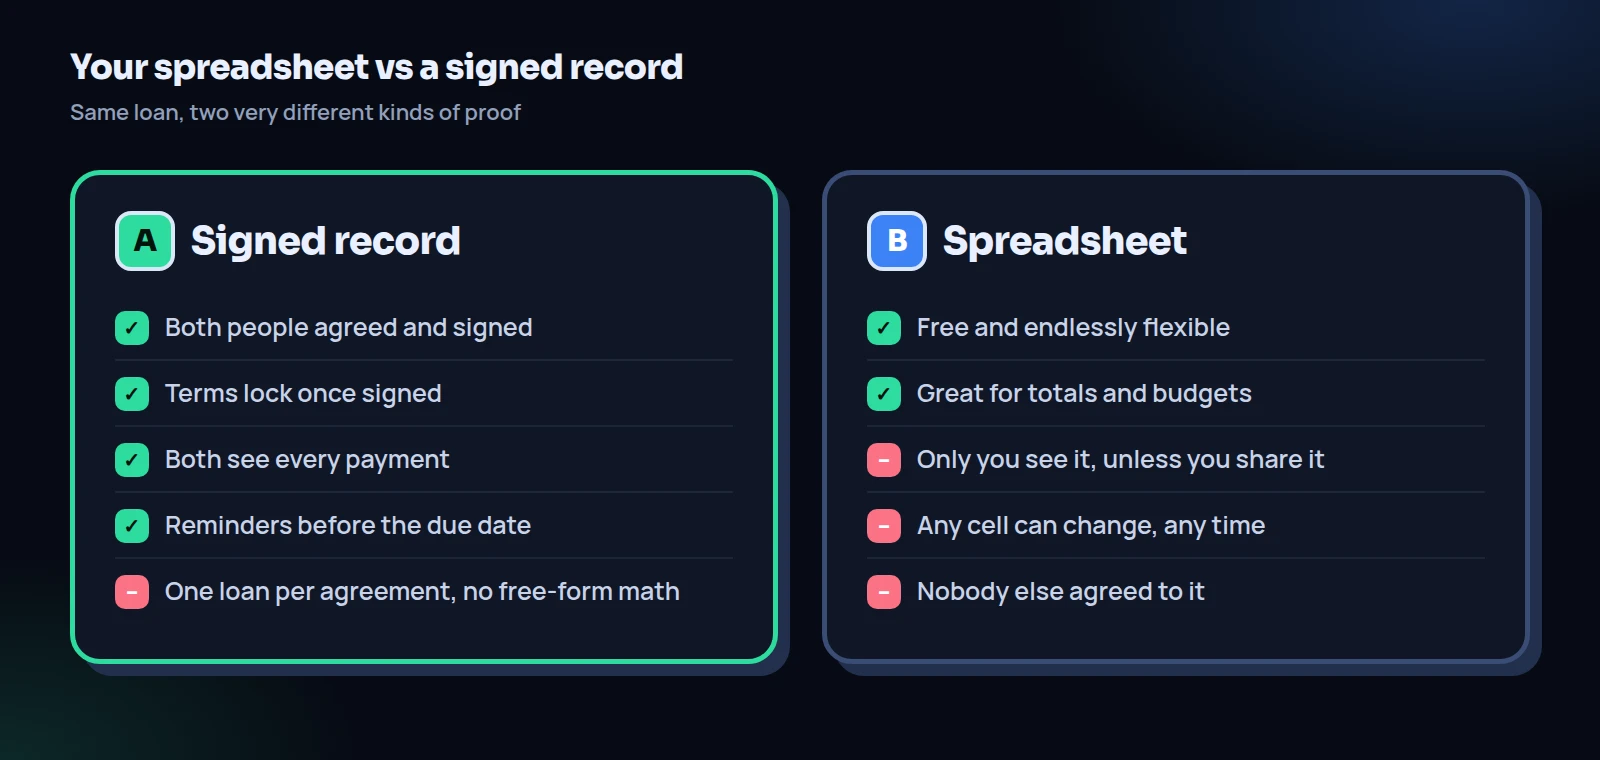
The fairest comparison is between the two tools that actually track balances over time. Both can tell you that Reese owes $1,200. Only one of them can tell you that Reese agrees.
What spreadsheets do well
- Free, and you probably already know how to use one.
- Any layout, any formula, any chart you can imagine.
- Great for the whole picture: all loans, all currencies, your budget around them.
- Easy to share a read-only copy with a partner or tax preparer.
Where spreadsheets fall short for loans
- One-sided: the borrower never agreed to your rows.
- Editable forever, so a number from March can change in May without a trace most people would notice.
- No signatures, so nothing shows intent to borrow and repay.
- No reminders; you still send the awkward text.
- One broken formula and every balance below it is wrong.
What happened with Cameron and Reese
Example
Reese borrowed $1,800 in January to cover a gap between jobs. They agreed by text: $300 monthly from February. Cameron logged it in the spreadsheet. By June, the sheet said $600 paid and $1,200 left. Reese was sure it was $1,200 paid. Reese had paid $300 twice by Venmo, which Cameron had logged, and had also handed over $600 in cash at a birthday dinner in April. Cameron remembered the dinner. Cameron did not remember any cash.
Nobody lied. Cash at a party, two glasses of wine in, is exactly the kind of payment that slips between memories. The spreadsheet couldn’t help, because it only contained what Cameron typed. The chat couldn’t help either, because nobody had texted “got the $600, thanks!” that night.
They settled it the way most friends do: they split the difference and moved on, a little cooler toward each other. With a shared record, the cash would have been recorded by either of them that night, with a note, and the other would have seen it the next morning. If it hadn’t been recorded, the absence would have been obvious in April, when memories were fresh, not in June.
A spreadsheet records what you believe. A signed record shows what you both agreed.
What about chat history?
Chats deserve more credit than they get. A chat thread is the one informal record where both people speak in their own words, with timestamps. “Can I borrow $1,800 till I start the new job?” followed by “yes, 300 a month from Feb works” is a real agreement, and chat history is often the first thing people dig out when a loan goes sideways.
The problems are practical. The key message is buried between birthday plans and memes. Phones get replaced and backups fail. Terms get renegotiated across three different threads and a voice note. And the chat never totals anything: you can prove what was promised in January, but not what’s left in June.
Our advice: let the chat be where the deal happens, then copy the deal into a signed record the same day. Paste the key line into the agreement’s notes (“Agreed by text on Jan 12: $300 monthly from Feb 1”). The conversation stays human, and the record stays findable.
What any good loan record needs
Whichever side of the IOU app vs spreadsheet debate you land on, a record that holds up has the same five parts:
- Both full names, and which one is the lender.
- The exact amount and currency, and the date the money moved.
- The repayment plan: amounts and dates, or a final due date.
- Evidence that both people agreed: signatures, or at minimum a written “yes” from each.
- A log of every payment, with dates and a reference you can match to a bank or app statement.
A spreadsheet can hold parts 1, 2, 3 and 5 perfectly well. It’s part 4 it can’t do on its own, and part 4 is the one that matters when memories differ.
Why “signed by both” matters
Three reasons, from the everyday to the formal.
It’s the same number for both of you. In IOUEZ, a shared agreement is one record two people look at. When either records a payment, the other sees it, and the balance is the same on both screens. That alone prevents most disagreements.
It can’t drift. Once both people sign a shared agreement, the amount, currency, interest and due date lock. Nobody can “remember” $1,500 when you both signed $1,800. Notes and spreadsheets can be edited at any time, and there’s usually no trace that anything changed.
It shows intent. In the US, the federal ESIGN Act says a signature or contract can’t be denied legal effect just because it’s electronic. And intent matters beyond court. The IRS says that to deduct a nonbusiness bad debt, you must show that at the time of the transaction you intended to make a loan and not a gift. A signed agreement with dates and amounts says that plainly; a row in your private spreadsheet says much less.
What IOUEZ doesn’t do (yet)
An honest comparison has to include the gaps. If one of these matters to you, a spreadsheet alongside IOUEZ covers it well.
- Signed group balances. IOUEZ groups split shared costs and suggest who pays whom, but nobody signs a group balance. If someone ends a trip owing a larger amount they’ll repay over months, move it into a signed agreement between the two of you, as we show in our playbook for trips, roommates and events.
- Currency conversion. Balances are kept per currency, never converted. That’s deliberate for loans, but a spreadsheet is better for “what’s my total in dollars today”.
- Custom analysis. Charts by category, interest projections, budgets: export a CSV (or, depending on your plan, an Excel workbook) from the web app’s Settings or the Android app, and analyze it in a spreadsheet.
- An iPhone app. There’s a web app and an Android app. On an iPhone, you use the web app in the browser.
The time cost is worth counting too. A spreadsheet costs nothing to start, then a few minutes every time a payment comes in, plus the occasional evening untangling a formula. A signed agreement costs two minutes to create and sign, and then each payment is a few taps by whoever sent it. Reminders run on their own, so the most time-consuming part of informal lending, chasing, mostly disappears.
Our view: the IOU app vs spreadsheet choice isn’t either-or. Use the signed record as the source of truth for each loan, and use a spreadsheet for everything you’d like to calculate about your loans.
Pick this if…
Use these questions to choose for a specific loan.
Is it under $50, between people who trust each other completely?
→A note or a chat message is fine. Don’t over-engineer lunch money.
Is it a larger amount, or repaid over several months?
→Use a signed record, so both people see the same plan and every payment.
Would losing it, or a disagreement about it, hurt the relationship?
→Signed record, no question. That’s exactly what it’s for.
Do you want totals across many loans, budgets or charts?
→Add a spreadsheet on top, fed by CSV exports. Keep the signed record as the source of truth.
Is it a group expense with several people?
→A IOUEZ group for the math and the settle-up. Anything that will take months to repay becomes a signed agreement.
A quick test for your own records
Here’s a five-minute way to settle the IOU app vs spreadsheet question for yourself. Pick your largest open loan and ask the other person one question: “How much do you think is left?” Don’t share your number first.
If their answer matches yours to the dollar, your current system is working, whatever it is. Keep going. If it’s off by even one payment, you’ve found the disagreement while it’s small and friendly, and you’ve found the reason to move that loan into a record you both sign. Cameron tried this with two other friends after the Reese episode. One matched. The other was off by $150, a forgotten Venmo payment that Cameron had never logged, and it took thirty seconds to fix because both of them were looking for it together.
Moving from a spreadsheet to signed records
You don’t need to migrate everything. Start with open loans only; settled ones can stay in the spreadsheet as history.
For each open loan, have a two-minute conversation first: “I’m moving our loan into an app so we both see the same numbers. My sheet says $1,200 left; does that match yours?” If it doesn’t, sort it out now, before anyone signs. Then create the agreement in IOUEZ for the remaining balance, with a note such as “Balance carried over from original $1,800 loan of Jan 2026; $600 paid before this agreement.” Both sign, and from then on payments go in the app.
Cameron and Reese did exactly that for the remaining $600 in July. The last two payments went into IOUEZ, each recorded the day it was sent, and the agreement closed in September with both of them looking at the same zero. Cameron still has the spreadsheet; it now imports the CSV export once a quarter for the budget tab.
Watch out
Don’t create a new signed agreement for the original full amount if part has already been repaid. Sign for what’s actually still owed, and note the history. Otherwise the clean new record starts with a wrong number.
For a step-by-step on the first agreement, see how to create and sign your first agreement online; for the conversation before the money moves, our guide on how to lend money to a friend; and for copies you control, exporting your records.
Frequently asked questions
IOU app vs spreadsheet: which is better?
For recording a loan between two people, a signed record, because both people agree to it and the core terms can’t change quietly. For analysis and budgets, a spreadsheet. Many people use both.
Is a chat message enough proof of a loan?
It’s better than nothing, since it shows both voices. But it’s easy to lose, hard to search and rarely states clear terms. A short signed agreement is much clearer.
Can I import my spreadsheet into IOUEZ?
There’s no spreadsheet import. Create agreements for your open loans, using the remaining balance and a note about the history.
Can I get my IOUEZ data into a spreadsheet?
Yes. In the web app, Settings has Export your data: agreements as a CSV file on every plan, or an Excel workbook with agreements, payments and groups, depending on your plan. The Android app exports debts and payments as CSV files, and each agreement has a Print / PDF option.
Is a notes app good enough for small loans?
For small amounts between people who trust each other, often yes. Once a loan is big enough that a disagreement would sting, or is repaid over several months, move it into a record you both sign.
Do both people need the app for a signed record?
For each person to sign on their own device and see every payment, yes. Otherwise you can sign together in person on one device, or keep a private record.
Sources
- U.S. Code, 15 U.S.C. § 7001, General rule of validity (ESIGN Act), Legal Information Institute, Cornell Law School.
- Internal Revenue Service, Topic no. 453, Bad debt deduction, on showing you intended a loan and not a gift.
- Internal Revenue Service, How long should I keep records?, on how long to keep records that support a tax return.